This article was inspired by a snippet from @elonmusk’s 2026 Davos speech: “if you have ubiquitous AI that is essentially free or close to it, and ubiquitous robotics, then you will have an explosion in the global economy and expansion the global economy that is truly beyond all precedent."”
I. The Temporal Variable in Standard Metrics
Standard valuation benchmarks—GDP, P/E multiples, and Yield—are the industry’s lingua franca. While ubiquitously adopted, they are rarely scrutinized through a First Principles lens.
The critical observation is that GDP (annualized output), P/E (current price relative to a fiscal period’s earnings), and Yield (annualized return) are all functions of a singular, often overlooked variable: Time.
Given a mean human life expectancy of 80 years, our financial models naturally default to a 12-month fiscal cycle as the baseline unit of measurement. However, we must consider the valuation implications if an investor’s horizon extended to 9,000 years—mirroring the longevity found in the Sumerian King List—or if market participants consisted of AIs with infinite operational lifespans.
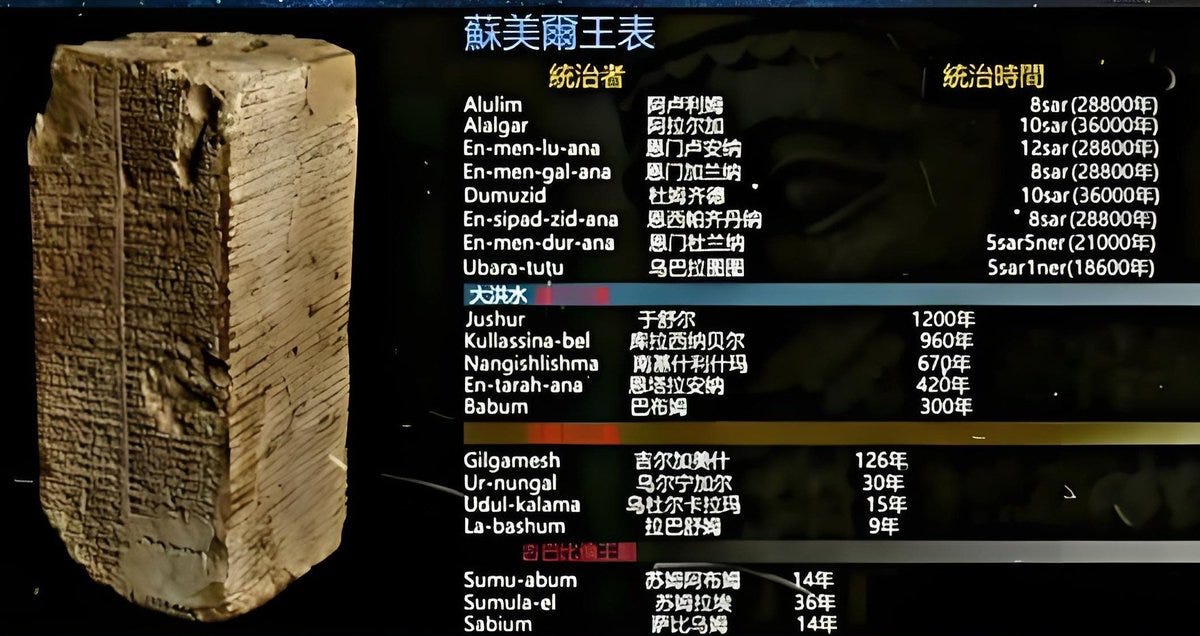
II. Re-evaluating Multiples through Longevity
Theoretical stress-testing of valuation models reveals a startling realization: our perception of “value” is tethered to biological mortality.
Consider the current equity landscape:
S&P 500 Shiller PE: ~40.35. This cyclically adjusted ratio indicates a significant premium over historical means.
NVIDIA (NVDA) Trailing PE: ~45.2 – 45.4.
A multiple of 40x is widely characterized as “expensive.” Yet, the consensus that 40x is high—while 400x or 4,000x is unthinkable—is largely an empirical conclusion based on historical data rather than logical necessity.
From a First Principles perspective, a P/E of 40 implies that, holding earnings constant, the cost of entry ($P$) requires a 40-year duration to achieve principal recovery. Effectively, human market participants price assets using their own 80-year lifespan as a subconscious reference. If the dominant market participants shift from humans to infinite-lived AI entities, the ceiling for P/E ratios and “asset bubbles” could expand exponentially.
III. The Compounding Power of a 9,000-Year Horizon
As of 2023, approximately 90% of Warren Buffett’s net worth was generated after his 65th birthday—a testament to the terminal velocity of long-term compounding.
If Buffett’s investment horizon were 9,000 years, short-term volatility over a 30-year window would become statistically irrelevant noise. Would the market continue to afford Berkshire Hathaway a forward P/E of sub-23? Furthermore, as Family Offices transition from traditional multi-generational human management to AI-augmented autonomous systems, the scale of capital accumulation will shift by several orders of magnitude.
IV. Implications for Digital Asset Valuations
Current crypto-asset valuations (secondary markets) remain primarily driven by liquidity cycles, mindshare, and capital structure. No single institution currently possesses the scale to dictate these markets. However, we anticipate two potential evolutionary paths:
Fundamental Convergence: As the industry matures toward cash-flow and utility-driven models, valuation frameworks will likely converge with P/E logic, potentially adopting the “9,000-year” expanded time preference.
The AI-Dominant Economy: Should the sector transition to an AI-led economic engine, our current analytical tools will become obsolete. In an environment where humans are effectively “primitive observers” to AI-driven high-frequency shifts, traditional valuation may give way to pure probabilistic speculation.
So the ultimate question is, how much bubble it could expend to in the limit of human’s mentality? As your AI to get your own answer!